What is the scope and industry significance of the Flight Navigation System Market?
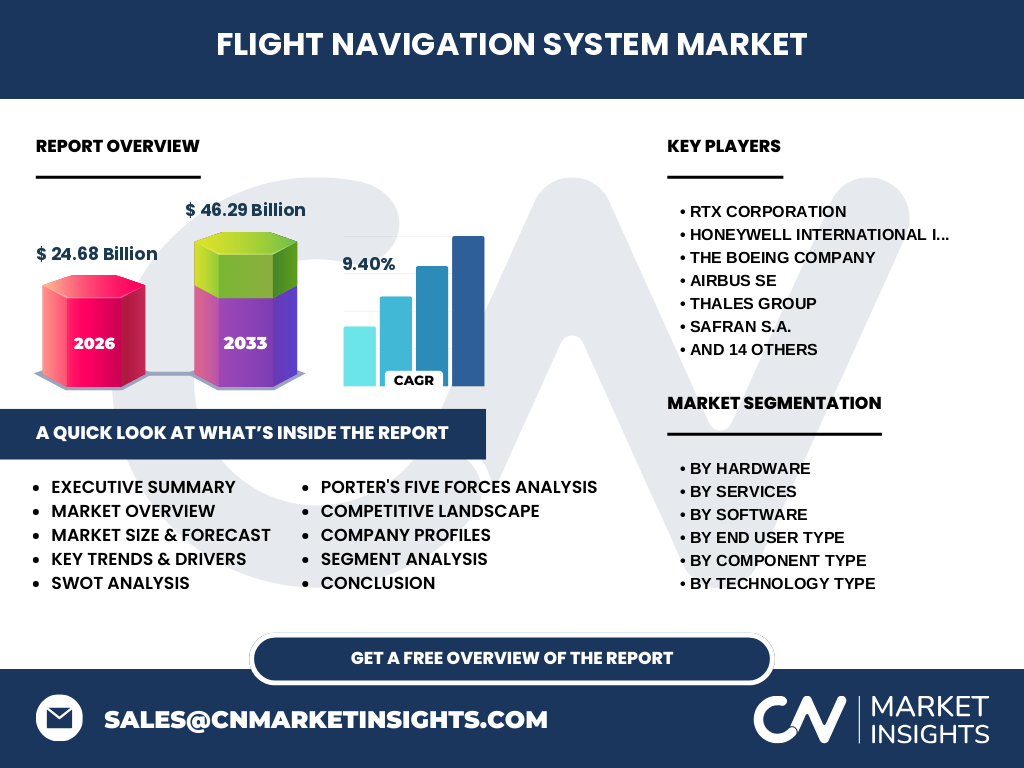
Our analysis indicates that the Flight Navigation System Market represents a critical aerospace sector valued at $24.68 Billion in 2026. This market encompasses advanced avionics essential for precision routing, regulatory compliance with the Federal Aviation Administration (FAA) and European Union Aviation Safety Agency (EASA), and secure military deployments across global airspaces.
Structural Growth Drivers and Market Restraints in Avionics
The market is propelled by a robust 9.40% CAGR driven by surging demand for next-generation NextGen air traffic management and autonomous flight capabilities. However, supply chain bottlenecks for rare-earth raw materials like neodymium and stringent FAA certification timelines act as primary operational restraints.
Emerging Technological Trends Shaping Flight Navigation Systems
Hybrid navigation architectures combining Global Navigation Satellite Systems (GNSS) with anti-jam Inertial Navigation Systems (INS) are redefining cockpit technology. These innovations mitigate severe GPS spoofing threats encountered in contested regional airspaces, directly favoring tech-forward suppliers.
How did the COVID-19 pandemic permanently alter the industry recovery trajectory?
While commercial aviation groundings severely depressed avionics retrofits during 2020, our research shows accelerated post-pandemic modernization. Airlines prioritized predictive maintenance software and digital flight planning tools to optimize fuel burn amidst volatile jet fuel pricing.
Competitive Benchmarking and Strategic Dynamics
Industry consolidation defines the landscape, with prime defense contractors and avionics giants dominating tier-1 supply chains. Competitors leverage proprietary software ecosystems and strategic military-commercial dual-use portfolios to capture high-margin government and OEM contracts.
Executive Summary of the Flight Navigation System Market Report
Driven by unprecedented technological integration, the market is poised to reach $46.29 Billion by 2033. Stakeholders must navigate stringent cybersecurity mandates and supply chain vulnerabilities while capitalizing on the explosive growth of unmanned aerial systems and urban air mobility.
Long-Term Market Forecast from 2027 to 2033
Expanding at a projected 9.40% CAGR from 2027 through 2033, the market will scale from its baseline to hit $46.29 Billion by 2033. This trajectory reflects heavy capital expenditure in regional air mobility and military defensive avionics upgrades.
Granular Segmentation Analysis Across Hardware, Software, and Services
The market is segmented by hardware, software, and services. Hardware includes Flight Management Systems and navigation sensors; software covers air traffic management platforms; services feature critical maintenance and installation support necessary for fleet airworthiness compliance.
Geographic Distribution and Regional Market Performance
North America anchors global demand due to high concentrations of commercial fleet operators and advanced military modernization programs governed by the Department of Defense. Meanwhile, the Asia-Pacific region demonstrates the fastest regional expansion driven by surging commercial airline passenger traffic.
In-Depth Regional Review of High-Growth Aerospace Hubs
European markets prioritize strict EASA environmental and noise-abatement routing compliance, while Asia-Pacific investments focus on massive airport infrastructure expansions in emerging aviation hubs, directly boosting local installation and training services demand.
Company Profiles and Strategic Positioning of Leading Innovators
Industry leaders like RTX Corporation, Honeywell International Inc., and Thales Group command major market share through integrated avionics suites. Specialized players like Garmin Ltd. and Universal Avionics capture vital general and business aviation segments with intuitive cockpit displays.
Porter's Five Forces Analysis of the Aviation Ecosystem
Supplier power remains moderate due to specialized rare-earth material requirements, whereas buyer power is high given intense competition among commercial aircraft OEMs like The Boeing Company and Airbus SE demanding cost-optimized avionics integration.
SWOT Analysis of the Global Avionics Sector
Key strengths include unmatched technological precision and deep OEM integration; weaknesses involve high R&D cost burdens. Opportunities lie in autonomous flight control integration, while threats stem from sophisticated cyber threats targeting satellite navigation links.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material refiners supplying semiconductor silicon and inertial sensor metals, flows through tier-1 hardware and software developers like Northrop Grumman Corporation and Safran S.A., and culminates with commercial, military, and general aviation end-users.
Strategic Investment Insights and High-Potential Areas
Investors should target niche software innovators specializing in AI-driven collision avoidance and autonomous flight control algorithms. These segments offer superior operating margins and lower capital expenditure barriers compared to heavy hardware manufacturing.
Conclusion and Definitive Industry Takeaways
The trajectory toward $46.29 Billion by 2033 highlights an era of aggressive technological evolution. Companies that successfully fuse hybrid navigation redundancy with robust cybersecurity protocols will capture dominant market positioning.
Research Methodology and Data Triangulation Framework
Our baseline estimates are rigorously triangulated by combining international civil aviation trade registry data, primary stakeholder interviews with chief technology officers, and secondary macroeconomic indicators regarding global defense budgets and commercial aircraft backlog orders.
Scope of the Report and Analytical Parameters
This report covers global market dynamics for flight navigation systems across commercial, military, and general aviation end-user types from 2026 to 2033. Exclusions involve localized recreational drone navigation hardware not adhering to certified civil aviation standards.
Recent Developments, Partnerships, and Product Launches
Recent strategic moves feature L3Harris Technologies Inc. and Elbit Systems Ltd. securing major defense contracts for next-generation helmet-mounted display navigation, alongside Garmin Ltd. rolling out advanced synthetic vision software updates for general aviation retrofit markets.